Hello and welcome to our Spring report.
After a generally subdued winter following government policy announcements and a May interest rate rise that affected sentiment across property markets, everyone seems to be asking the same question: what happens from here?
Let’s be brave and have a look.
There are many individual circumstances that determine whether someone can or is willing to buy or sell real estate, but there are also some overriding principles that influence almost everyone. One of those is that people generally dislike change and uncertainty. If you are contemplating a large financial decision, you naturally want the clearest runway ahead of you possible.
That runway has been particularly opaque in 2026. Changes in government policy, the prospect of higher interest rates and international instability have all created uncertainty. Whether these things directly affect an individual buyer or seller is almost secondary. It is the disruption to our view of the future that affects confidence and when people are uncertain, they tend to wait.
The important thing to remember is that we have seen this many times before.
We are currently experiencing an ebb in the property market and, like most ebbs, it can feel while you are living through it as though the world is in peril. Negative headlines dominate. Buyers become cautious. Properties take longer to sell. Sellers become nervous. Everyone starts wondering what everyone else knows that they don’t.
Yet if we look backwards, we don’t have to look very far to find other periods when caution and pessimism were equally prevalent. The early 1990s recession ushered in a prolonged period of subdued property activity. By the late 1990s, the mood had changed and a very strong property cycle followed. By 2003, after years of substantial growth, optimism was everywhere. Interest rates rose, market conditions changed and suddenly confidence evaporated.
The market eventually gathered momentum again, only for the Global Financial Crisis to arrive in 2008. At the time, it genuinely felt as though the financial world might be ending. Share markets fell dramatically, banks around the world were in trouble and property buyers understandably became extremely cautious. Governments and central banks responded. Interest rates fell dramatically, policy settings changed and confidence eventually returned. Foreign investment became increasingly influential and Australian buyers, seeing competition return, started joining in.
Fear of buying was gradually replaced by fear of missing out.
And around we went again. Then came COVID.
In early 2020, the outlook for property was frightening. Borders closed, unemployment was expected to soar and there were predictions of significant falls in property values. For a while, very few people knew what to do.
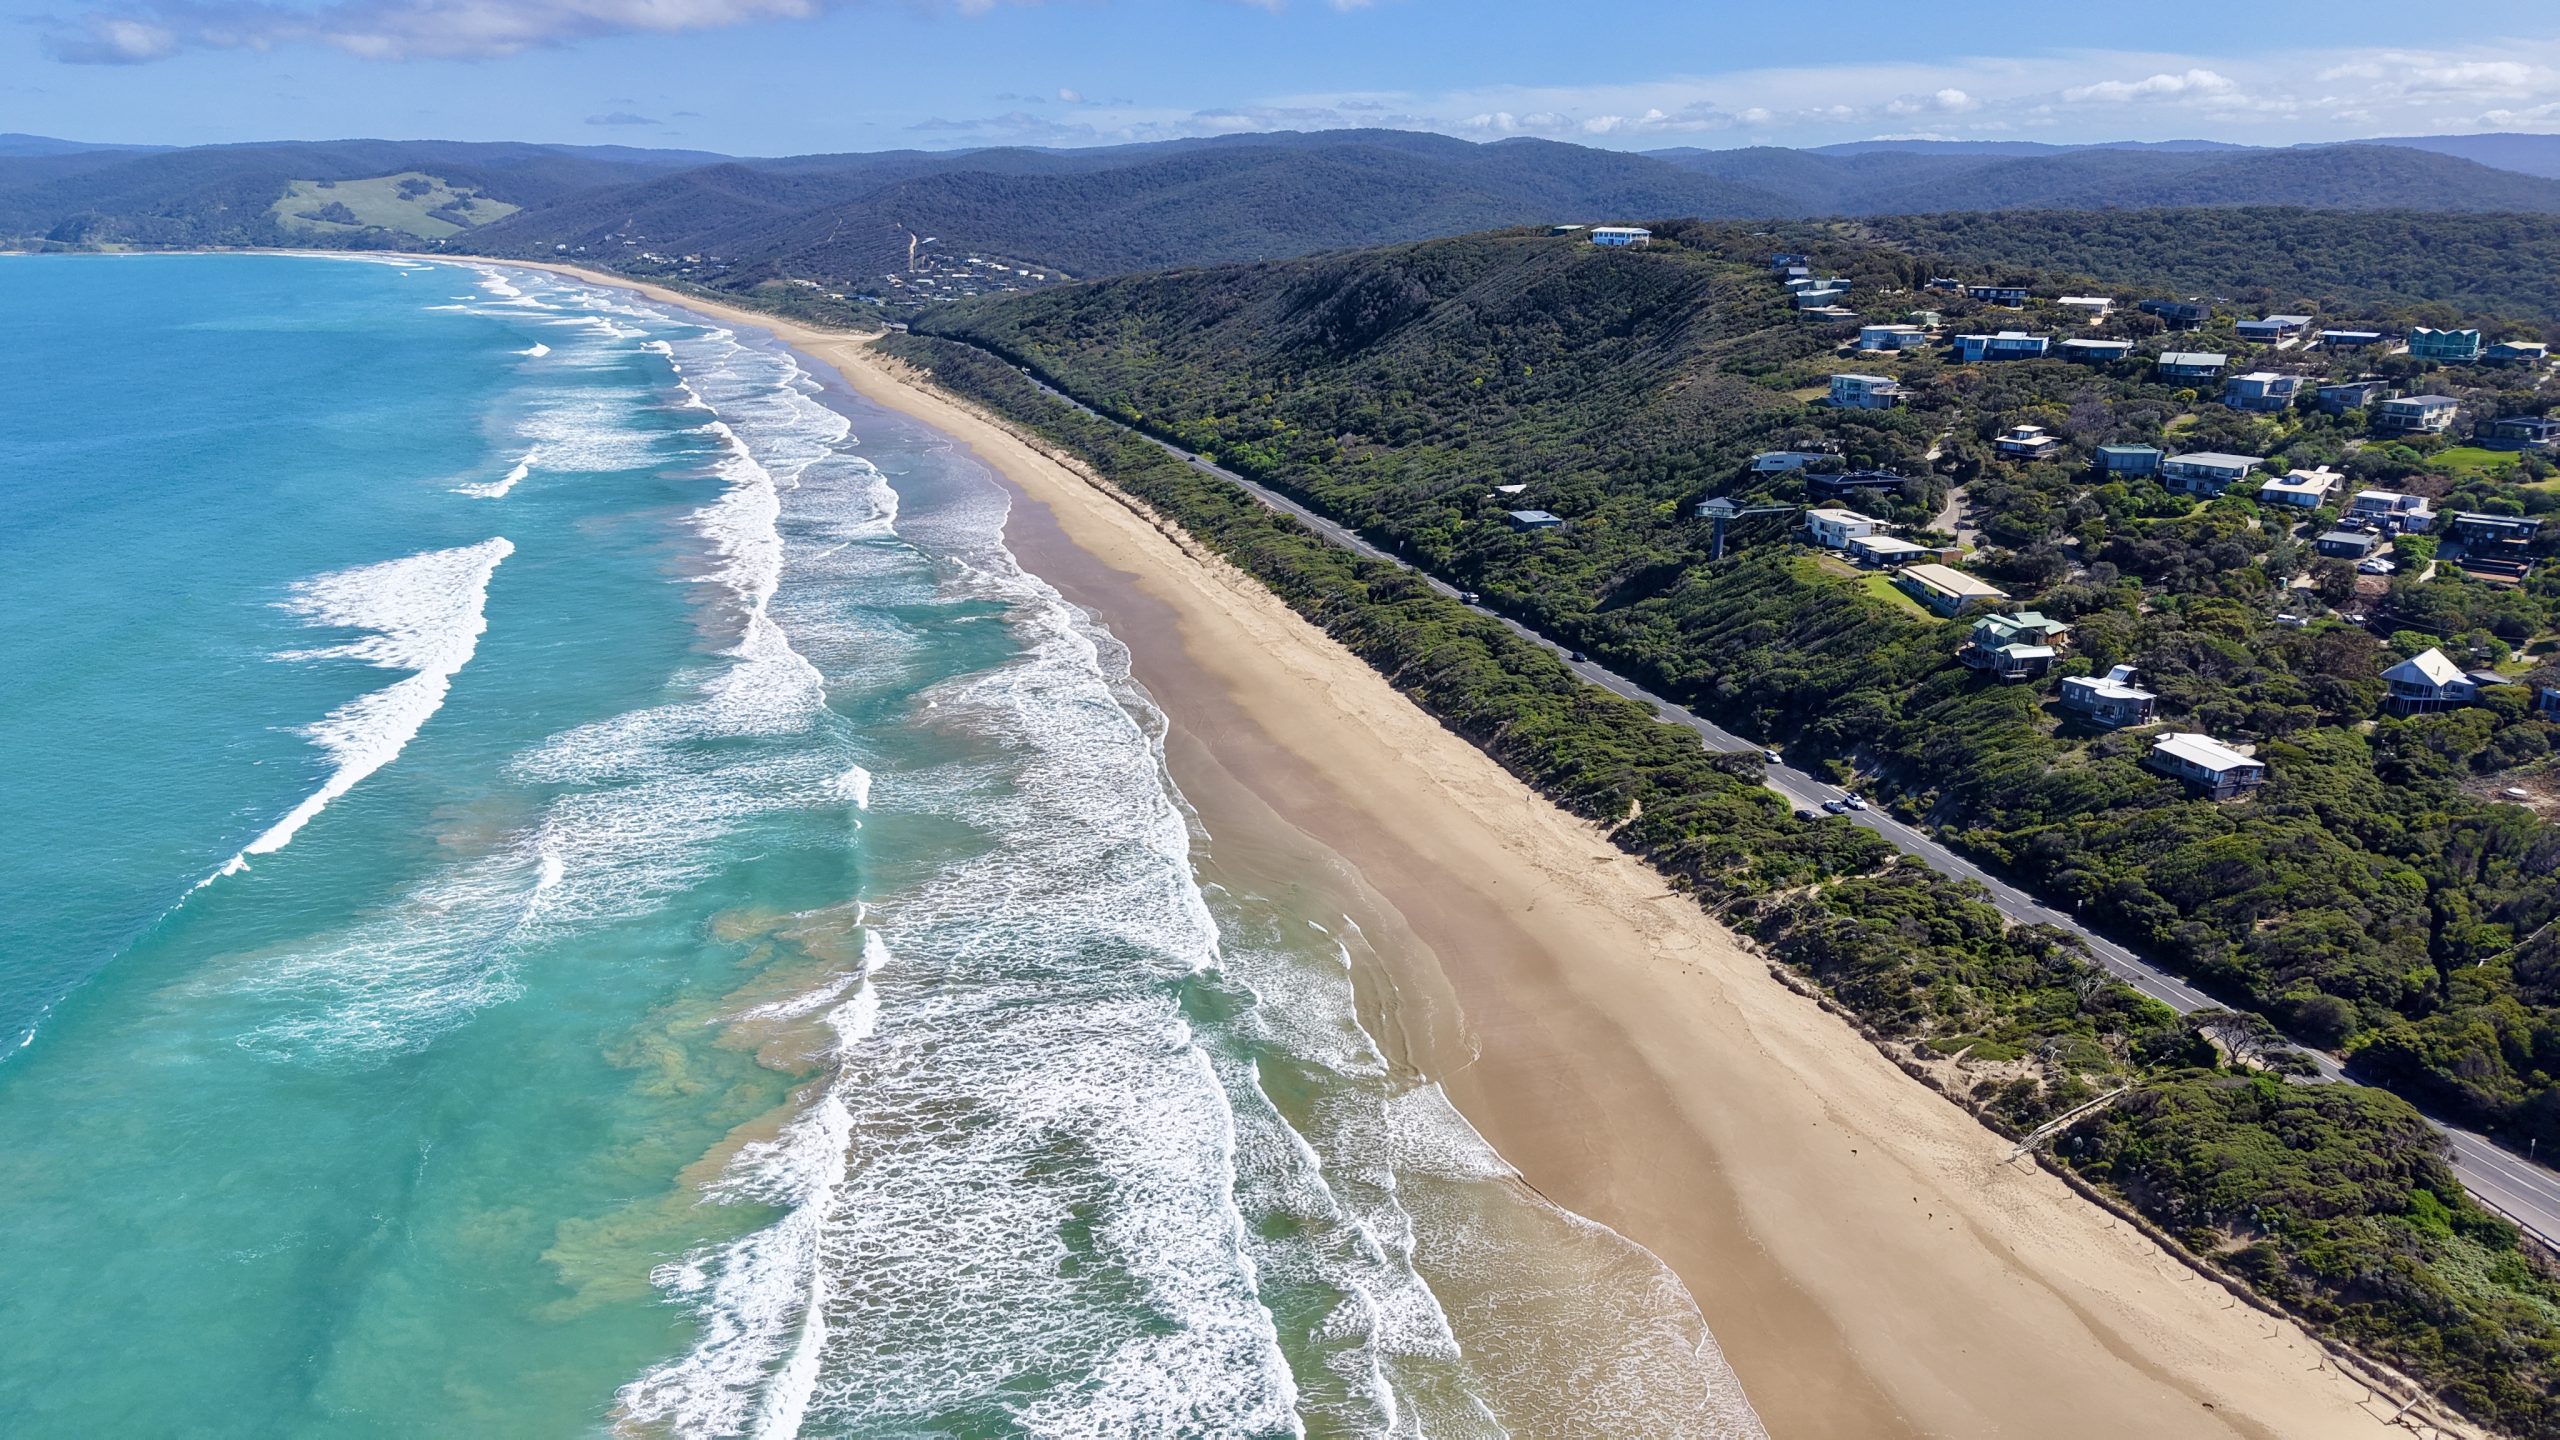
Interest rates were subsequently slashed, enormous amounts of stimulus entered the economy and something unexpected happened. People’s priorities changed. Suddenly, space, lifestyle and the ability to work from home became incredibly important. Regional property markets, including our own coastal market, experienced extraordinary demand. Buyers who had been frightened to act months earlier became frightened of missing out.
The herd had changed direction again. This is perhaps the most fascinating aspect of property cycles. Human beings are herd animals. We take comfort from doing what everyone else appears to be doing. When five people are competing for a property, a sixth buyer feels reassured that they should probably be competing for it too. When nobody else appears interested, that same buyer can become concerned there must be something they are missing.
At the top of a cycle, we hear: “If we don’t buy now, we’ll never get in.”
At the bottom, we hear: “We might wait and see what happens.”
Both reactions are completely understandable. But both are driven, at least partly, by emotion. The irony is that periods that ultimately prove to have been excellent buying opportunities rarely felt comfortable at the time. If they had felt comfortable, everyone would have been buying and the opportunity probably wouldn’t have existed.
Similarly, the easiest time psychologically to buy is often when confidence is high, prices have been rising and everyone around you believes property is a great investment. History tells us that can sometimes be precisely when greater caution is warranted.
Nobody reliably rings a bell at the bottom or the top.
What we can say after watching property markets for many years is that neither optimism nor pessimism lasts forever. Markets ebb and flow because circumstances change. Interest rates change. Governments change policy. Population grows. Credit becomes easier or harder to obtain. Economic conditions improve and deteriorate.
But something else changes too. People change their minds.
Today’s cautious buyer becomes tomorrow’s motivated buyer. The person waiting for certainty eventually realises complete certainty never arrives. A few properties start selling, other buyers notice, confidence slowly returns and eventually the herd begins moving in the other direction. Usually, we only recognise the turning point afterwards.
So as we enter Spring 2026, perhaps the most useful thing is not to try to predict the exact month that conditions will improve. It is simply to recognise where we are in the cycle.
For buyers, that means there may be less competition, more time to consider a property carefully and greater scope to negotiate than there was during the busiest parts of the cycle. For sellers, it means pricing realistically, presenting the property well and understanding that patience may be required.
The market may not turn all at once. It may begin with one well-priced property selling, then another. Buyers will notice. Sellers will notice. Confidence will gradually return, and the conversation will change. History shows it always does.